.webp)
For about a decade, automation meant one thing. Somebody found a boring, repetitive task, a bot got built to click through it, and finance reported the hours saved. RPA was a very fast intern who follows the checklist perfectly and panics the moment the checklist is wrong.
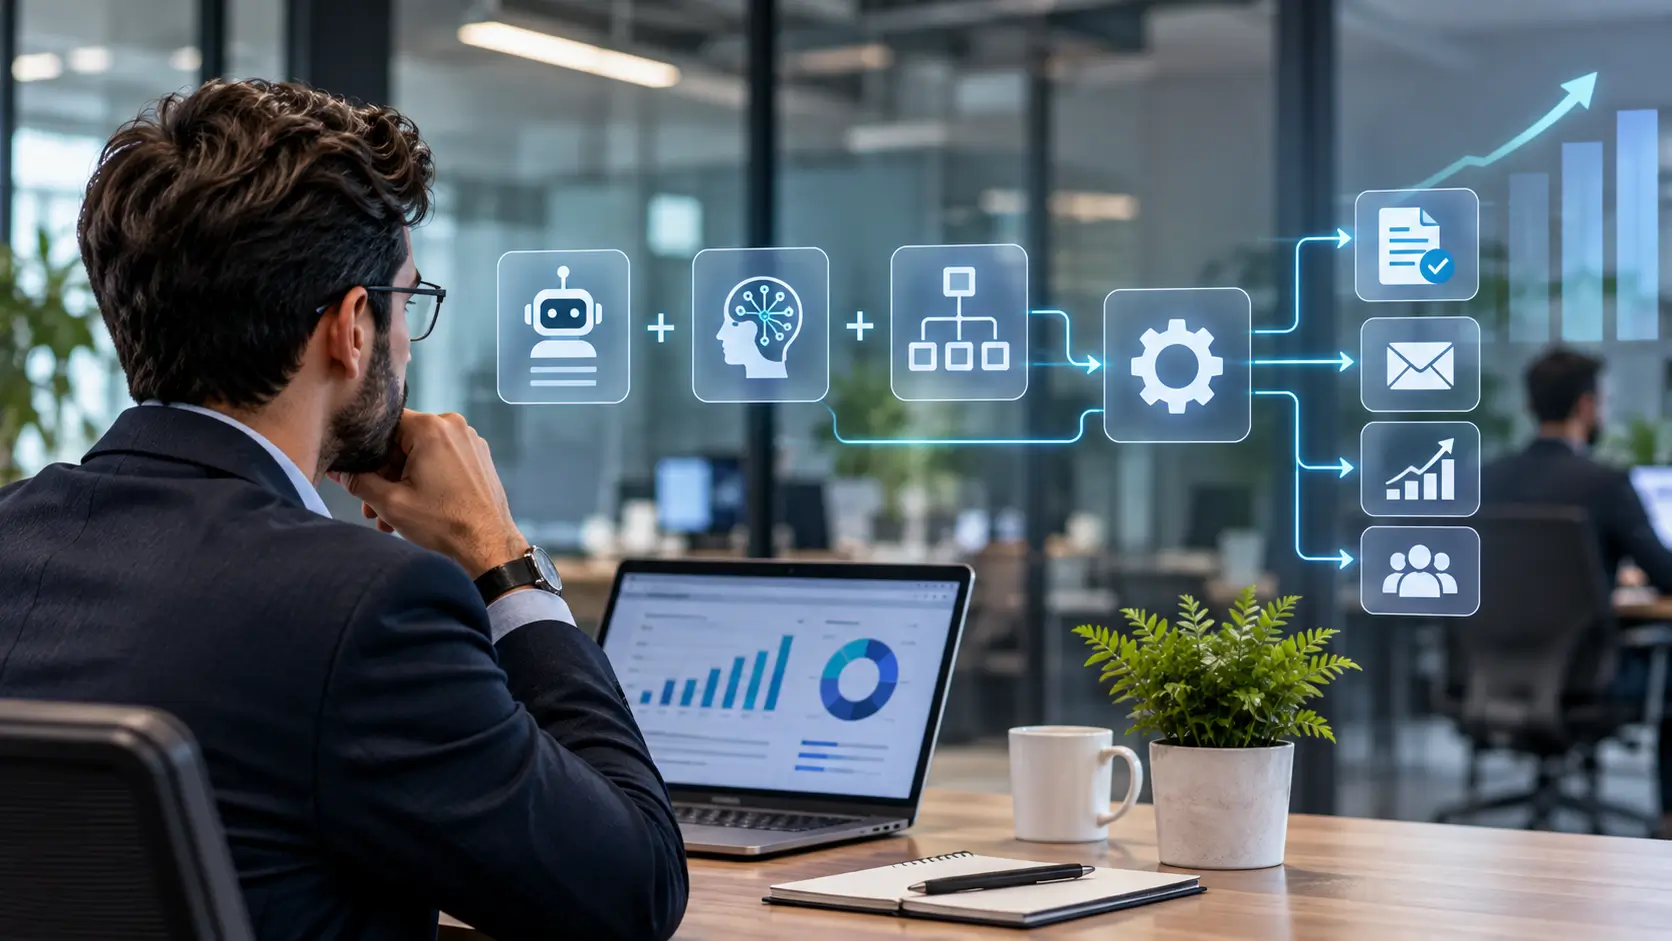
That picture is out of date in 2026. Hyperautomation, which stacks RPA, AI agents, document processing, process mining and orchestration into one system, is changing how companies look at their own operations. The money flowing into it shows how seriously buyers now take that change.
What Hyperautomation Actually Means Now
Hyperautomation is not a product. It is the practice of automating as much of a business process as possible by combining deterministic tools (rules and scripts) with probabilistic tools (AI models that reason and decide). The old RPA layer still handles the predictable work. AI agents handle the exceptions, the messy inputs and the judgment calls. An orchestration layer sits on top and decides which one does what, and when a human steps in.
UiPath’s CEO Daniel Dines made a useful argument on the company’s latest earnings call. When AI makes building software cheaper, the value moves to whoever can run and govern that software reliably at scale. That is the whole thesis of the orchestration layer.
How Automation Changes the Way You See a Business
The biggest change is not technical. It is how leaders now read their own company.
From departments to processes. An org chart shows who reports to whom. A process view shows how an invoice, a claim or a customer request actually travels through the company. Automation forces you to draw that second map, and most companies are surprised by what it shows. Process mining tools now do this from system logs, so the map reflects what really happens and not what the policy manual says.
From tasks to outcomes. RPA automated a keystroke sequence. Agentic automation is pointed at a goal, such as resolving a claim denial or clearing a compliance alert. UiPath’s recent healthcare and financial crime launches work this way. The unit of automation is a result, not a click.
From headcount to capacity. Leaders now ask how much work the digital workforce can absorb and where humans add the most judgment. Headcount planning and automation planning are becoming the same conversation.
From systems of record to systems of action. Your ERP and CRM used to store things. Now agents act on top of them. ServiceNow describes its platform as a control tower for exactly this reason, because someone has to watch what the agents are doing.
From a project to an operating model. Automation used to belong to a center of excellence. Microsoft says Power Platform now has 80 million monthly active users, up from 56 million a year earlier and 25 million in 2022. Automation is moving into the hands of ordinary business users, which makes governance a bigger problem than building.
The data backs the shift. UiPath reported that customers spending over 100,000 dollars a year who adopt its AI products spend nearly three times as much as those who do not. Gartner expects 40 percent of enterprise applications to include task specific AI agents by the end of 2026, up from under 5 percent in 2025.
The Market Numbers and Why They Disagree
Anyone quoting one number for this market is hiding something. The estimates are wildly different because the definitions are different.
Gartner measures the core RPA software market at roughly 3.6 to 3.8 billion dollars in 2024, growing between 14.5 and 18 percent depending on the Gartner document. That is the narrow, conservative view. Third party research houses put RPA at anywhere from 5.7 to 9.2 billion dollars in 2026 with growth forecasts that look wildly optimistic.
The broader hyperautomation category, which includes AI, process mining, orchestration and services, is sized much higher. Fortune Business Insights puts it at 65.2 billion dollars in 2026 and growing about 17 percent a year. TechSci Research puts 2025 at 45.85 billion dollars with growth near 19 percent a year. Applying those rates, the broad market lands somewhere between 65 and 77 billion dollars in 2027.
My own extrapolation of the Gartner trend puts core RPA software around 5.5 to 6 billion dollars in 2027. That is an estimate from me and not a Gartner forecast. The older forecast of 26 billion dollars by 2027 that still circulates was made in 2022 and mixes in services, so treat it as dated.
The Companies Doing the Work and What They Earn
UiPath is the public pure play. Fiscal 2026 revenue was 1.611 billion dollars, up 13 percent, with ARR of 1.853 billion dollars and its first full year of GAAP profitability. AI product ARR reached nearly 200 million dollars in the fourth quarter. In its second quarter of fiscal 2027 (ended July 2026), revenue was 410 million dollars, up 13 percent, ARR hit 1.938 billion dollars, and cloud ARR passed 1.3 billion dollars. Guidance for fiscal 2027, which ends in January 2027, is revenue of 1.789 to 1.794 billion dollars and ARR of 2.065 to 2.070 billion dollars. Even with a raised outlook, the stock fell sharply after the September report, because investors wanted faster growth.
ServiceNow is the biggest earner touching this space. Third quarter 2026 revenue was 4.106 billion dollars, up 20.5 percent, with subscription revenue of 3.988 billion dollars. Full year subscription guidance is about 15.785 billion dollars. Its AI annual contract value target for 2026 was raised twice, from 1 billion to 1.7 billion dollars. The catch is that GAAP profit fell and backlog growth is guided to slow in the fourth quarter.
Microsoft does not break out Power Automate revenue, so the best signal is usage. Its attended RPA license is 15 dollars per user per month, and unattended bots are an add on at around 150 dollars per bot per month. Cheap, bundled and everywhere. That pricing pressure is a real problem for pure play vendors.
Pegasystems had a rough quarter. Third quarter 2026 revenue was 393.4 million dollars, up 3 percent, and missed estimates by a wide margin. Pega Cloud ACV grew 20 percent to 976 million dollars, but total ACV growth slowed to 7 percent, and management dropped its earlier 15 percent ACV growth target and plans to trim headcount.
Appian is smaller and growing faster. It earned 726.9 million dollars in 2025, and second quarter 2026 revenue was 203.3 million dollars, up 19 percent, with cloud subscriptions up 23 percent.
Automation Anywhere is private, so revenue is not disclosed. The company said 61 percent of its fourth quarter software bookings came from AI products and its agentic customer base more than doubled. Its last funding round valued it at 6.8 billion dollars. A recent secondary market estimate is closer to 2.2 billion.
Others in Gartner’s RPA Magic Quadrant include SS&C Blue Prism, SAP, IBM, Salesforce and Samsung SDS.
What Revenue Looks Like Through 2027
These are my projections built on reported guidance, not company forecasts.
UiPath guides to about 1.79 billion dollars for fiscal 2027. At 11 to 13 percent growth, fiscal 2028 lands around 2.0 billion dollars, with ARR passing 2 billion dollars as management has said.
ServiceNow is on track for roughly 15.8 billion dollars in 2026 subscription revenue. If growth holds between 17.5 and 20 percent, 2027 comes in at roughly 18.5 to 19 billion dollars. Its first 2027 guidance, due with fourth quarter results, is the number to watch.
Appian consensus growth of 13.3 percent for 2026 and 10.6 percent for 2027 implies roughly 820 million dollars and then 910 million dollars. Pega’s older consensus is stale after its miss.
The pattern is the interesting part. The vendors growing fastest are the ones selling orchestration and governance. The ones selling bot licenses are growing in the low teens or worse.
Where This Goes Wrong
Be skeptical of the hype. Gartner warns that almost half of agentic AI projects will be scrapped by 2028, and that many vendors engage in agent washing, relabeling chatbots and RPA as agentic. It also says most organizations are adding AI agents next to RPA and BPA, not replacing them. One 2026 industry survey found 61 percent of businesses say their automation tools are underutilized, and fewer than 6 percent are close to autonomous operation.
There is also a dependency problem. Every layer you rent, whether bots, agents or orchestration, is a pricing lever someone else controls. Owning your core workflows and treating vendor platforms as replaceable parts is the safer long term position. And the more autonomy you hand to agents, the more you need a human who can see what they did and stop them.
What to Do With All This
Map your processes before you buy anything. Start with deterministic, high volume work where RPA still wins. Add AI agents only where exceptions are costing real money. Put governance and human review in from day one, and keep your process logic portable. The companies that treat automation as a way of seeing their business will get the revenue and savings. The ones that treat it as a bot shopping trip will get a pile of underused licenses.